The 'Dream Home' Trap: Why Most North Suburb Properties Are Liabilities
Your dream home in Wilmette might be your worst investment.
It sounds harsh, but the data doesn't lie. We’ve all driven through the tree-lined streets of the North Shore, admired the historic architecture, and thought, "That's a rock-solid asset." But if you’re looking to build wealth through real estate, you need to look past the curb appeal and into the spreadsheets.
In his classic book Rich Dad Poor Dad, Robert Kiyosaki redefined these terms simply: An asset puts money in your pocket every month. A liability takes money out.
It sounds elementary. But in today’s market, the vast majority of North Suburb properties are firmly in the liability category. When you buy an $800,000 house in Park Ridge because of the school district, the mortgage, the $15,000 Cook County tax bill, and the maintenance are bleeding you dry. That's not an investment; that's a lifestyle choice.
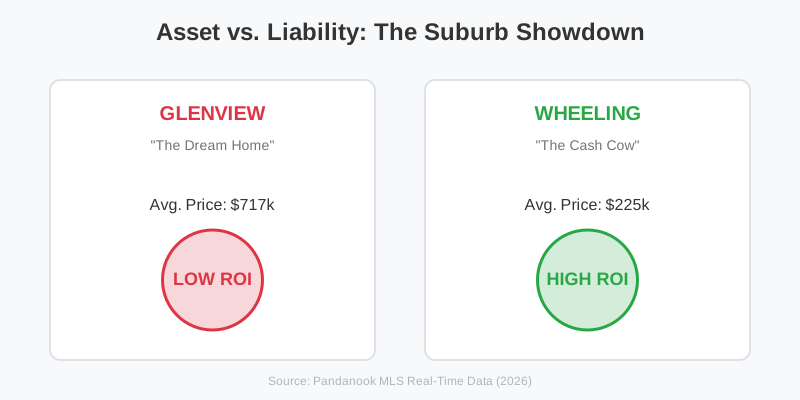
Asset vs. Liability: The North Suburb Comparison
| Characteristic | The Asset (The "Cash Cow") | The Liability (The "Dream Home Trap") |
|---|---|---|
| Primary Goal | Monthly cash flow & debt paydown | Appreciation & personal prestige |
| Rent-to-Price | > 0.7% (e.g., $1,800 rent on $250K price) | < 0.4% (e.g., $3,000 rent on $800K price) |
| Location | High-density, commuter-friendly pockets | Exclusive, low-density school districts |
| Property Taxes | Manageable relative to gross rent | High (often > 30% of gross rental income) |
| Example | A 2-bed condo in Des Plaines ($210K) | A 4-bed colonial in Wilmette ($1.2M) |
| Panda Nook ROI | Positive (+5% to +12%) | Negative (-10% to -25%) |
The Problem: The Negative ROI Norm
We track every active MLS listing in Illinois and run ROI calculations on all of them. When we zoom into 10 popular north suburbs, the results are staggering: the average ROI (at our standard 25% down baseline) is significantly negative. (Note: Our engine computes custom ROI based on your exact strategy—from 1% up to 100% cash—but we use 25% for our baseline investment analysis).
High purchase prices, combined with Cook County’s effective property tax rate of ~2.1% and current interest rates, have created a massive gap between what a property costs to own and what it can generate in rent.
North Suburbs Market Snapshot (May 2026)
| City | Active Listings | Avg Price | Avg ROI (25% down) | Listings > 5% ROI |
|---|---|---|---|---|
| Morton Grove | 14 | $533K | -6.6% | 0 |
| Des Plaines | 49 | $452K | -8.4% | 0 |
| Niles | 18 | $395K | -8.7% | 1 |
| Mount Prospect | 33 | $514K | -10.5% | 1 |
| Arlington Heights | 44 | $699K | -11.8% | 0 |
| Glenview | 34 | $1.22M | -13.1% | 0 |
| Park Ridge | 35 | $908K | -13.6% | 0 |
| Evanston | 40 | $901K | -16.4% | 0 |
| Wilmette | 13 | $1.62M | -17.0% | 0 |
The takeaway: Out of 280 rentable listings across 9 suburbs, only 2 have an ROI greater than 5%. That's less than 1%. If you're just browsing the MLS without a data-driven filter, you have a 99% chance of buying a liability.
What Makes a Property an Asset?
To find that elusive 2%, we use a rigorous framework. A property only qualifies as a "Panda Nook Asset" if it meets three criteria:
- Positive Net Cash Flow: After mortgage (PITI), HOA fees, maintenance reserves, and vacancy — the property must put money in your pocket. Our engine factors in actual HOA amounts from MLS data, not estimates.
- Rent-to-Price Ratio > 0.7%: In the north suburbs, if a $300,000 property isn't renting for at least $2,100, the math rarely works. At today's rates, 1%+ is ideal — 0.7% is the absolute floor.
- Rental Eligibility Confirmed: Many condos and HOAs in towns like Evanston or Arlington Heights have rental caps. An asset isn't an asset if you aren't allowed to rent it out.
A note on our numbers: All cash flow figures in this post are net — they include mortgage payment, property taxes, HOA fees, insurance, and maintenance reserves. When we say "$407/mo cash flow," that's what hits your bank account after every expense is paid.
"Real Deals" — Proof the Strategy Works
While the averages are tough, investors who know how to find the 2% are thriving. Here are three real properties bought and rented within the last year that deliver double-digit returns:
Deal #1: 9405 Bay Colony Drive, Des Plaines
- Purchase Price: $180,000 (Closed Jan 2025)
- Monthly Rent: $2,100
- ROI (25% down): 10.91%
- Monthly Cash Flow: $407/mo
- Rent-to-Price Ratio: 1.17%
👉 View Listing on Panda Nook →
Deal #2: 408 Ridge Avenue, Evanston
- Purchase Price: $165,000 (Closed Feb 2025)
- Monthly Rent: $1,800
- ROI (25% down): 10.47%
- Monthly Cash Flow: $356/mo
- Rent-to-Price Ratio: 1.09%
👉 View Listing on Panda Nook →
Deal #3: 3515 Central Road, Glenview
- Purchase Price: $188,000 (Closed Jun 2025)
- Monthly Rent: $1,950
- ROI (25% down): 10.21%
- Monthly Cash Flow: $383/mo
- Rent-to-Price Ratio: 1.04%
👉 View Listing on Panda Nook →
How to Find the 2%
You don't need to be a math whiz to find these deals; you just need the right tools.
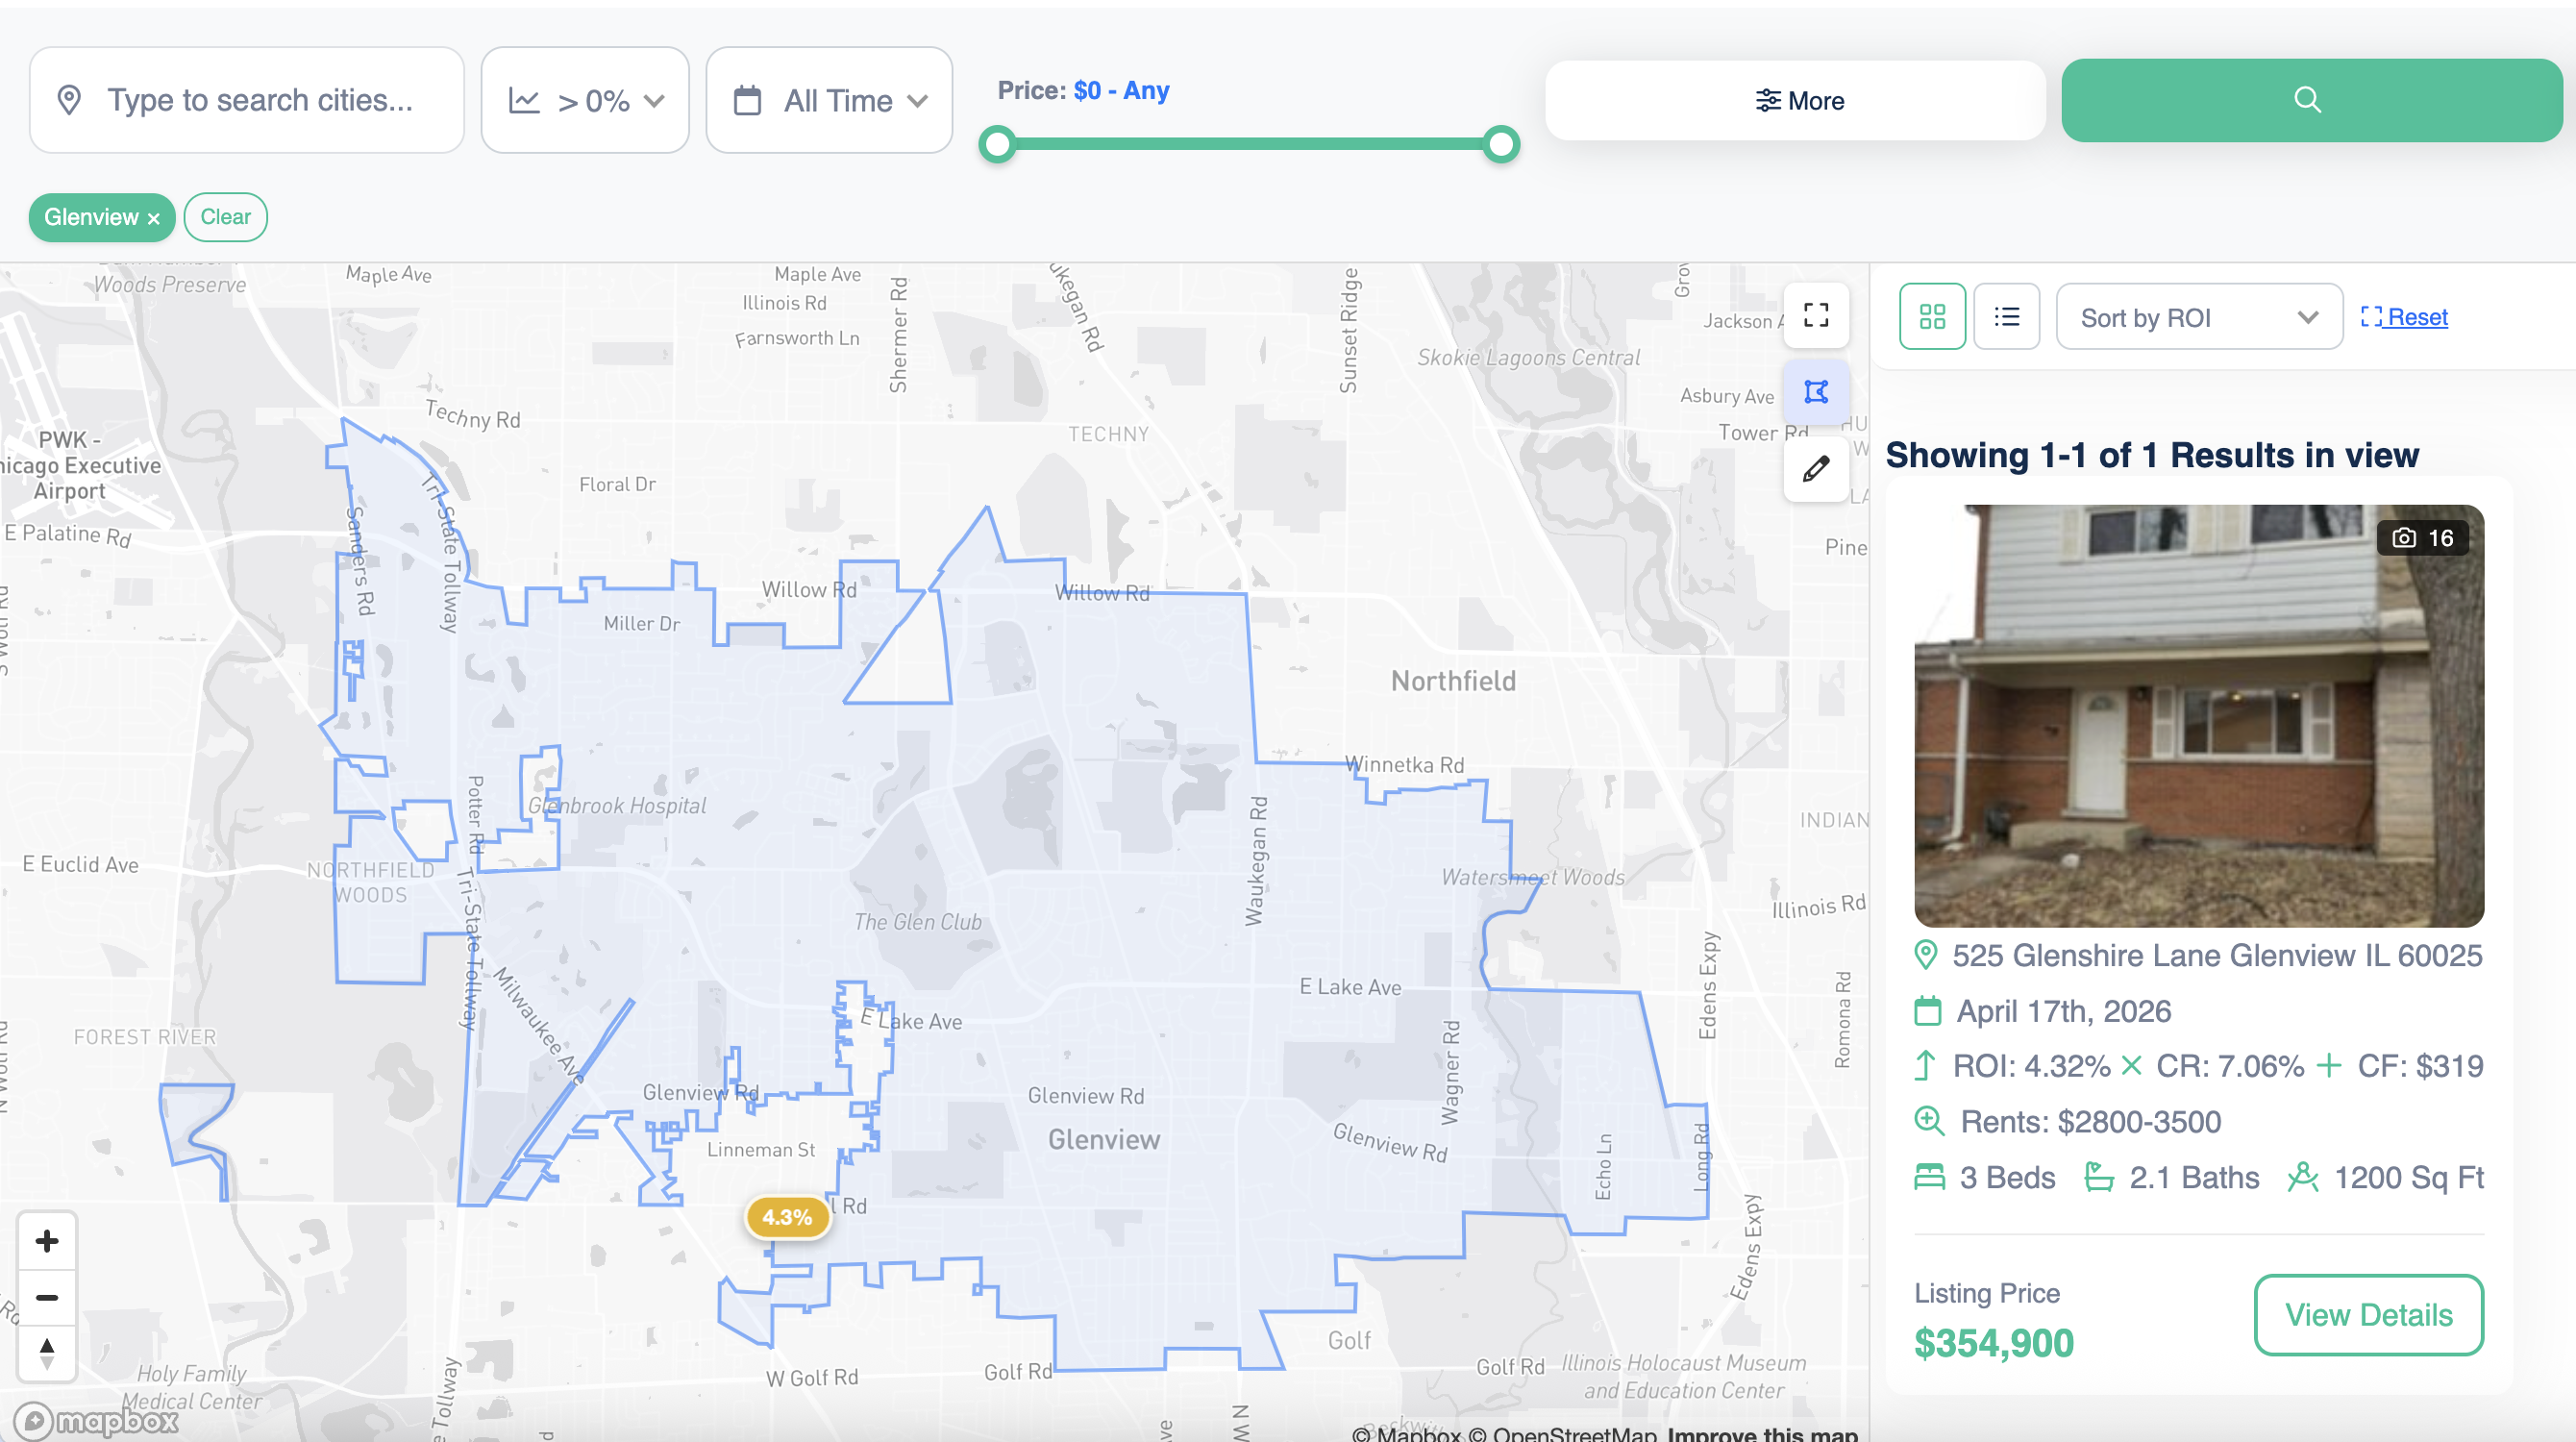
🔧 Try it yourself: Open the Panda Nook Map View and zoom into Glenview, Skokie, or Des Plaines.
Our map uses color-coded ROI markers:
* Green: Positive cash flow at 25% down (you can toggle this from 1% to 100% in the app). These are your assets.
* Yellow: Break-even.
* Red: Negative. You'd lose money every month.
The visual contrast makes it immediately obvious which pockets have investment potential and which don't. While most markers in the north suburbs are red (liabilities), the green ones stand out as the 2% that are actual assets. Note: Clicking a marker shows the full ROI breakdown (requires login).
By filtering for "ROI > 5%" and "Rental Allowed," you can narrow down 400+ listings to the 9 that actually matter in about 30 seconds.
3 Listings Worth Looking At Right Now
If you're ready to stop looking at dream homes and start looking at cash cows, here are three active rentable listings that pass the test:
415 E Lincoln St, Mount Prospect ($250,000)
- ROI: 10.94% | Cash Flow: $570/mo
- Why it works: Low entry point with high rental demand. Perfect starter rental. View Listing →
9731 N Fox Glen Dr, Niles ($214,900)
- ROI: 5.37% | Cash Flow: $241/mo
- Why it works: Affordable entry in Niles with confirmed rental eligibility and positive monthly cash flow. View Listing →
7315 Arcadia St, Morton Grove ($524,900)
- ROI: 3.9% | Cash Flow: $427/mo
- Why it works: 4-bed single-family in Morton Grove with strong rental comps ($3,550–$4,000/mo for similar homes). Solid positive cash flow in a suburb where most listings are negative. View Listing →
These won't last. Listings with positive ROI go under contract 2.5x faster than the market average. If one of these catches your eye, reach out to us — we can help you move fast and secure the deal before it's gone. And to make sure you never miss the next one: create a free Panda Nook account and set up automated investment alerts. It's free, no strings attached.
Next: Episode 02 | In the next episode, we'll show you why the 2% don't last — and how to get notified the moment a profitable listing hits the MLS before your competition even knows it exists.